Define What Is Economics Core Principles And Applications
Table of Contents
- Core Definition and Scope of Economics
- Fundamental Principles Distinguishing Economics from Other Social Sciences
- Microeconomics vs. Macroeconomics: Focus and Applications
- Economic Agents and Their Roles in Decision-Making
- Historical Evolution of Economic Thought
- Chronological Development of Major Economic Schools
- Historical Events Shaping Economic Theories
- Key Economic Models and Tools
- Foundational Economic Models and Their Assumptions
- Mathematical Modeling of Human Behavior: Consumer Choice Theory
- Process of Building an Economic Model: From Data to Policy
- Economic Systems and Institutional Frameworks
- Comparison of Centralized and Decentralized Economic Systems
- Hierarchical Roles of Economic Institutions
- Property Rights and Legal Systems: Empirical Influence on Economic Behavior
- FAQ
- define what is home economics?
- explain what is economics?
- define utility is economics?
- define economics class 11?
- define economics according to adam smith?
- define economics according to lionel robbins?
Economics is the systematic study of how societies allocate scarce resources to satisfy unlimited human needs, serving as the foundation for understanding both individual decisions and global systems. From the micro-level interactions of consumers and firms to the macro-scale dynamics of inflation and GDP, this discipline bridges theory and real-world impact, shaping policies that influence everything from wages to environmental sustainability. By examining the interplay between scarcity, choice, and institutional frameworks, economics reveals why markets thrive, why governments intervene, and how historical events reshape economic thought—offering tools to analyze challenges from inequality to technological disruption.
The field’s evolution—from Adam Smith’s invisible hand to behavioral economics’ critiques of rational decision-making—demonstrates its adaptability in addressing complex systems. Whether through mathematical models predicting consumer behavior or comparative analyses of centralized versus decentralized economies, economics provides a lens to evaluate efficiency, equity, and growth. This exploration will dissect its core principles, historical foundations, and modern applications, illustrating why economics remains indispensable in navigating an interconnected world.

Core Definition and Scope of Economics
Economics examines how societies allocate limited resources to satisfy unlimited human wants, a fundamental tension that underpins all economic analysis. Unlike other social sciences, economics distinguishes itself through its rigorous focus on scarcity, rational decision-making, and the optimization of resource allocation under constraints. The discipline operates at two primary levels—microeconomics and macroeconomics—each addressing distinct yet interconnected dimensions of economic activity, from individual choices to aggregate outcomes.
The study of economics begins with the recognition that resources—labor, capital, land, and entrepreneurship—are finite, while human desires are boundless. This scarcity necessitates trade-offs, forcing economic agents to make deliberate choices about production, consumption, and distribution. These decisions are governed by incentives, costs, and benefits, which economists analyze using theoretical models and empirical evidence. The field’s uniqueness lies in its ability to quantify trade-offs, predict behavioral responses to policy changes, and evaluate efficiency in markets and economies.
Fundamental Principles Distinguishing Economics from Other Social Sciences
Economics differs from disciplines such as sociology or political science by its emphasis on methodological individualism and optimization under constraints. While sociology studies social interactions and norms, economics dissects how individuals and institutions respond to incentives shaped by resource limitations. Political science examines governance and power structures, but economics evaluates how these structures influence economic outcomes, such as growth, inequality, or public welfare.A core principle is opportunity cost, the value of the next best alternative foregone when a choice is made. This concept underscores the trade-offs inherent in decision-making, whether by a consumer selecting between goods or a government allocating tax revenue. Additionally, economics relies on ceteris paribus (all else equal) assumptions to isolate variables, enabling causal analysis. Unlike qualitative fields, economics often employs mathematical models, statistical tools, and experimental methods to test hypotheses, bridging theory with real-world data.
Microeconomics vs. Macroeconomics: Focus and Applications
Microeconomics and macroeconomics represent two complementary branches of economics, each addressing distinct yet interdependent questions. Microeconomics analyzes the behavior of individual agents—households, firms, and industries—within markets, focusing on price determination, resource allocation, and efficiency. Macroeconomics, conversely, examines aggregate economic phenomena, such as national income, unemployment, inflation, and economic growth, often requiring policy interventions to stabilize or stimulate economies.The distinction between the two is not absolute; microeconomic principles underpin macroeconomic outcomes, while macroeconomic policies (e.g., interest rates) influence microeconomic decisions. For instance, a firm’s hiring decisions (micro) may respond to macroeconomic trends like GDP growth or inflation. Below is a comparative table illustrating key differences:
| Concept | Micro Focus | Macro Focus | Example |
|---|---|---|---|
| Supply and Demand | Determines prices and quantities of individual goods/services in specific markets (e.g., apples, housing). | Analyzes aggregate supply/demand curves to assess overall price levels (e.g., inflationary pressures). | Micro: Rise in smartphone demand increases Apple’s iPhone prices. Macro: High aggregate demand leads to general price inflation. |
| Inflation | Examines how price changes for specific goods affect consumer purchasing power (e.g., gasoline prices). | Measures overall price level changes (CPI, PPI) and their impact on economic stability. | Micro: Higher wheat prices reduce consumer budgets for other staples. Macro: Persistent inflation erodes savings and reduces real wages. |
| GDP Growth | Evaluates contributions of individual sectors (e.g., tech, agriculture) to national output. | Tracks total economic output (GDP) and per capita income to assess living standards and policy effectiveness. | Micro: Tesla’s expansion boosts U.S. manufacturing output. Macro: 3% GDP growth indicates economic expansion. |
| Unemployment | Studies labor market dynamics (e.g., frictional vs. structural unemployment in specific industries). | Measures national unemployment rates (U-3, U-6) and their link to economic cycles. | Micro: Layoffs in coal mining increase local unemployment. Macro: 5% unemployment signals a healthy labor market. |
Economic Agents and Their Roles in Decision-Making
Economics identifies four primary economic agents whose interactions drive market outcomes and policy responses. Each agent operates under distinct objectives, constraints, and incentives, shaping production, consumption, and governance. Below are their roles, categorized for clarity:Households are the fundamental units of consumption and labor supply, maximizing utility (satisfaction) subject to budget constraints. Their decisions—such as spending on education, saving, or purchasing durable goods—are influenced by income levels, interest rates, and expectations of future prices. For example, rising rent costs may force households to reduce discretionary spending, indirectly affecting aggregate demand.These agents interact through markets, where prices serve as signals for resource allocation. Households supply labor and demand goods, firms supply goods and demand labor/capital, and governments intervene to address market imperfections or achieve social objectives. The dynamic between these agents—mediated by institutions, laws, and technology—defines the structure and performance of economies worldwide.Firms are profit-maximizing entities that allocate resources to produce goods and services. Their behavior is governed by cost structures, technology, and market competition. Firms determine wages, prices, and investment levels, which in turn affect employment and economic growth. A firm’s decision to automate production (e.g., using AI) may increase productivity but reduce labor demand, illustrating the trade-offs between efficiency and social equity.
Governments act as regulators, providers of public goods (e.g., infrastructure, defense), and redistributors of income via taxation and welfare programs. Their role extends to correcting market failures (e.g., externalities like pollution) and stabilizing economies through monetary and fiscal policy. For instance, a government may impose carbon taxes to internalize environmental costs, altering firm and household behavior.
Financial Markets facilitate the flow of capital between savers and borrowers, influencing investment, consumption, and economic stability. Institutions such as banks, stock exchanges, and central banks determine interest rates, credit availability, and asset valuations. The 2008 financial crisis demonstrated how disruptions in financial markets can trigger macroeconomic downturns, emphasizing their systemic importance.
Historical Evolution of Economic Thought
The development of economic thought reflects humanity’s evolving understanding of production, distribution, and resource allocation. Major schools of economic theory emerged in response to historical crises, technological advancements, and ideological shifts, shaping policies from laissez-faire capitalism to state interventionism. This evolution demonstrates how economic ideas are not static but adapt to address contemporary challenges, such as inequality, sustainability, and market failures. Below, the chronological progression of key schools is outlined, alongside their foundational contributions and the external factors—political movements, wars, and industrial revolutions—that influenced their formation.Chronological Development of Major Economic Schools
Economic theories have evolved in distinct phases, each responding to societal transformations. The following table summarizes the Era, Key Thinkers, and Core Contributions of foundational schools, illustrating their chronological and conceptual development.| Era | Key Thinker | Core Contribution |
|---|---|---|
| 18th Century (Mercantilism to Classical Economics) | Adam Smith (1723–1790) |
|
| Late 18th–Early 19th Century (Classical Economics) | David Ricardo (1772–1823), Thomas Malthus (1766–1834) |
|
| Mid-19th Century (Marginal Revolution) | William Stanley Jevons (1835–1882), Carl Menger (1840–1921), Léon Walras (1834–1910) |
|
| Late 19th–Early 20th Century (Institutional and Marxian Economics) | Karl Marx (1818–1883), Thorstein Veblen (1857–1929) |
|
| Early 20th Century (Keynesian Revolution) | John Maynard Keynes (1883–1946) |
|
| Mid-20th Century (Neoclassical Synthesis and Austrian School) | Friedrich Hayek (1899–1992), Milton Friedman (1912–2006) |
|
| Late 20th–21st Century (Behavioral and Heterodox Economics) | Daniel Kahneman (b. 1934), Amartya Sen (b. 1943), Esther Duflo (b. 1972) |
|
Historical Events Shaping Economic Theories
Economic theories rarely develop in isolation; they emerge as responses to crises, technological disruptions, and geopolitical shifts. The following events precipitated major policy and theoretical adjustments, demonstrating the dynamic interplay between economics and history.-
Industrial Revolution (1760–1840):
The shift from agrarian to industrial economies exposed inefficiencies in mercantilist policies, prompting Smith’s defense of free markets. Urbanization and wage labor also fueled Marx’s critique of capitalist exploitation, as factories concentrated labor under capitalist ownership.Adam Smith’s Invisible Hand: "By directing that industry in such a manner as its produce may be of the greatest value, he intends only his own gain, and he is in this, as in many other cases, led by an invisible hand to promote an end which was no part of his intention." (Wealth of Nations, 1776)
These contrasting views illustrate how philosophy (Smith’s liberalism vs. Marx’s dialectical materialism) shaped economic narratives.Karl Marx’s Labor Theory of Value: "The value of a commodity is determined by the socially necessary labor time required to produce it." (Capital, 1867)
-
Great Depression (1929–1939):
The collapse of global markets and mass unemployment discredited classical economics’ assumption of self-correcting markets. Keynes’ General Theory (1936)
Key Economic Models and Tools
Economic analysis relies on structured frameworks to simplify complex real-world phenomena, enabling predictions and policy recommendations. Foundational models—such as the Circular Flow Diagram, Supply-Demand Framework, and IS-LM Model—provide intuitive representations of market interactions, while mathematical tools like utility functions and optimization formalize decision-making processes. These tools, however, operate within defined assumptions that may not fully capture systemic complexities, necessitating complementary approaches (e.g., experimental or computational models) to address limitations in modeling human behavior and dynamic systems.
Foundational Economic Models and Their Assumptions
Economic theory employs abstract models to isolate key variables and derive testable hypotheses. Below is a comparative analysis of three core models, highlighting their structural assumptions, predictive capabilities, and inherent limitations in a tabular format.
Model Assumptions Predictions Criticisms Circular Flow Diagram - Two-sector economy (households and firms).
- Perfect competition with no market failures.
- Fixed factor mobility and homogeneous goods.
- Exclusion of government, foreign trade, and financial markets.
- Illustrates interdependence between production and consumption.
- Explains equilibrium in closed economies via income-expenditure balance.
- Serves as a pedagogical tool for introductory macroeconomics.
- Ignores income inequality and wealth distribution.
- Overlooks externalities (e.g., pollution, public goods).
- Simplifies labor markets by assuming full employment.
- Fails to account for dynamic changes (e.g., technological progress).
Supply-Demand Framework - Rational actors maximizing utility (consumers) or profit (firms).
- Perfect information and no transaction costs.
- Homogeneous goods and price-taking behavior.
- Ceteris paribus (all else equal) condition.
- Determines equilibrium price and quantity.
- Explains effects of shifts in supply/demand (e.g., taxes, subsidies).
- Foundation for welfare economics (consumer/producer surplus).
- Assumes linear preferences and no behavioral biases.
- Fails to model market power (monopolies, oligopolies).
- Ignores network effects and non-price factors (e.g., brand loyalty).
- Limited applicability to labor markets or public goods.
IS-LM Model - Fixed price level and short-run analysis.
- Closed economy with no capital flows.
- Linear investment (I) and liquidity preference (LM) functions.
- Government policy instruments (fiscal/monetary) as exogenous.
- Explains equilibrium in goods (IS) and money (LM) markets.
- Predicts effects of fiscal/monetary policy on output and interest rates.
- Foundation for Keynesian stabilization policies.
- Ignores expectations and adaptive behavior.
- Assumes rigid prices/wages, inconsistent with long-run dynamics.
- Excludes financial market frictions (e.g., credit constraints).
- Limited to small open economies without extensions.
Mathematical Modeling of Human Behavior: Consumer Choice Theory
Economists formalize decision-making using optimization frameworks, where agents allocate scarce resources to maximize utility or profit under constraints. Consumer choice theory exemplifies this approach, modeling preferences via utility functions and budget constraints to derive demand curves. The process involves:
1. Utility Function Specification: Agents rank bundles of goods (e.g., U(x,y) = xαyβ) based on marginal rates of substitution (MRS).
2. Budget Constraint: I = pxx + pyy, where I is income, px and py are prices.
3. Optimization: Maximize U(x,y) subject to the budget constraint, yielding demand functions (x(px, py, I)).
4. Comparative Static Analysis: Examines how changes in prices/income affect optimal choices.Real-World Constraints:
- Bounded Rationality: Consumers may not perfectly optimize due to cognitive limits (e.g., heuristic decision-making).
- Non-Monetary Factors: Preferences are influenced by social norms, habit formation, or irrationality (e.g., loss aversion).
- Market Imperfections: Asymmetric information or transaction costs distort predictions (e.g., search frictions in labor markets).
- Dynamic Preferences: Time-inconsistent behavior (e.g., procrastination) violates static utility maximization.
Example: The Engel Curve (derived from consumer theory) predicts that demand for inferior goods (e.g., generic brands) decreases as income rises. However, empirical data often shows non-linear patterns due to unmodeled factors like brand loyalty or cultural trends (e.g., organic food demand rising with income despite higher prices).
Process of Building an Economic Model: From Data to Policy
The development of an economic model follows a structured workflow, integrating theoretical foundations with empirical validation. Below is a hierarchical representation of the process, emphasizing iterative refinement and real-world applicability.
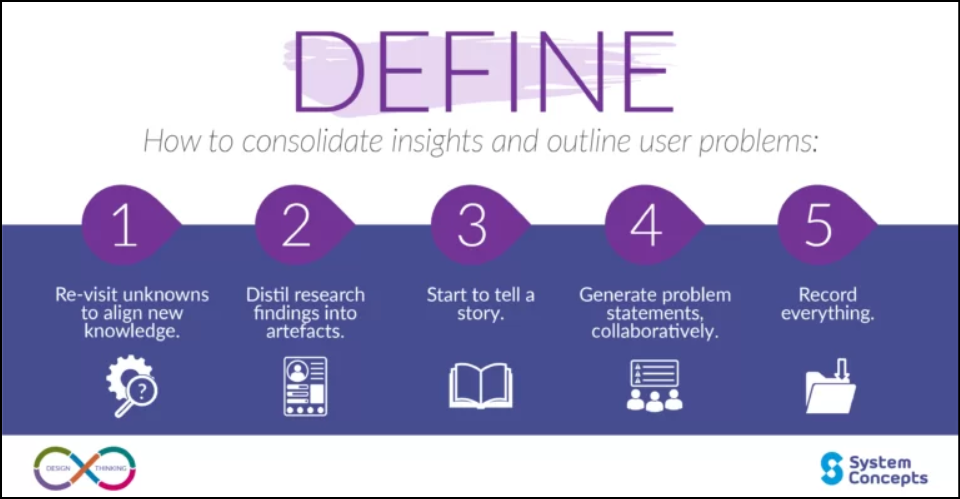
1. Problem IdentificationDefine the economic question (e.g., "How does minimum wage affect unemployment?").
2. Theoretical FrameworkSelect a model (e.g., labor supply-demand framework) and specify assumptions.
3. Data CollectionGather primary/secondary data (e.g., CPS for labor statistics, firm surveys).
Address missing data or measurement errors (e.g., imputation techniques).
Economic Systems and Institutional Frameworks
Economic systems and institutional frameworks serve as the structural backbone of resource allocation, production, and distribution within societies. The choice between centralized and decentralized models fundamentally shapes economic efficiency, equity, and dynamism. Institutions—ranging from central banks to labor unions—mediate interactions between economic agents, while property rights and legal systems establish the rules governing transactions. This section examines the comparative features of economic systems, the hierarchical roles of key institutions, and the empirical impact of legal frameworks on economic behavior, concluding with a procedural framework for evaluating systemic efficiency.
Comparison of Centralized and Decentralized Economic Systems
The dichotomy between centralized (command) and decentralized (market) economies reflects divergent approaches to coordination, incentives, and resource management. Below is a comparative analysis of their structural and operational features, illustrated through historical and contemporary examples.
Feature Centralized Example (Command Economy) Decentralized Example (Market Economy) Price Setting Mechanism Government or planning authorities determine prices via centralized quotas (e.g., Soviet Gosplan’s five-year plans). Prices often lack responsiveness to supply-demand dynamics, leading to chronic shortages or surpluses. Prices emerge from competitive interactions between buyers and sellers (e.g., U.S. agricultural commodity markets). Supply and demand directly influence prices, facilitating equilibrium. Innovation Incentives Limited, as rewards are tied to state approval rather than profitability. Innovation occurs primarily in defense or state-directed sectors (e.g., China’s "Great Leap Forward" steel production quotas stifled private R&D). Strong, driven by profit motives and intellectual property protections (e.g., Silicon Valley’s tech startups, incentivized by patents and venture capital). Resource Allocation Efficiency Inefficient due to information asymmetries and bureaucratic delays. Misallocation is common (e.g., Cuba’s sugar industry prioritization led to chronic food shortages). Generally efficient via price signals and competition, though market failures (e.g., monopolies, externalities) require regulatory intervention. Equity Outcomes Redistributive goals often prioritized, but implementation leads to inequality in access to goods/services (e.g., North Korea’s elite access to foreign goods). Income inequality persists, but mobility and opportunity vary by institutional design (e.g., Nordic model combines markets with strong welfare states). Adaptability to Shocks Rigid; slow to adjust to external shocks (e.g., USSR’s collapse accelerated by inability to compete with global markets post-1970s). Flexible; dynamic reallocation of resources (e.g., U.S. tech sector pivoting from hardware to software in the 1990s). Accountability and Corruption High corruption risks due to opaque decision-making (e.g., Venezuela’s PDVSA under state control). Transparency mechanisms (e.g., SEC regulations in the U.S.) reduce systemic corruption but do not eliminate rent-seeking. Hierarchical Roles of Economic Institutions
Institutions act as intermediaries that reduce transaction costs, enforce rules, and stabilize economic activity. Their hierarchical influence on resource allocation and systemic stability can be categorized as follows:
Macro-Stabilizing Institutions:
The interplay between these institutions determines whether an economy achieves Pareto efficiency (no reallocation improves welfare) or succumbs to market failures (e.g., public goods underprovision). For instance, the East Asian Miracle (1960s–1990s) demonstrated how coordinated institutional reforms—combining state-directed industrial policy with market mechanisms—accelerated growth.- Central Banks: Regulate monetary policy (e.g., Federal Reserve’s interest rate adjustments) to control inflation, unemployment, and liquidity. Their independence (e.g., ECB’s mandate) directly impacts growth volatility.
- Fiscal Authorities: Govern tax and expenditure policies (e.g., IMF’s structural adjustment programs in Latin America) to address fiscal imbalances and redistribute wealth.
- Stock and Commodity Exchanges: Facilitate capital allocation (e.g., NYSE’s IPO mechanisms) and price discovery for goods/services, though speculative bubbles (e.g., 2008 financial crisis) highlight systemic risks.
- Contract Enforcement Bodies: Courts and arbitration systems (e.g., Singapore’s International Arbitration Centre) reduce disputes in trade and investment, fostering long-term relationships.
- Labor Unions: Negotiate wages and working conditions (e.g., German co-determination model), influencing income distribution but potentially reducing labor market flexibility.
- Social Security Systems: Provide safety nets (e.g., Sweden’s universal healthcare) that stabilize consumption during economic downturns but may distort labor supply incentives.
- Antitrust Authorities: Prevent monopolistic practices (e.g., EU’s breakup of Microsoft in 2004) to preserve competitive markets.
- Environmental Agencies: Internalize externalities (e.g., China’s carbon trading pilot programs) but face trade-offs with economic growth.
Property Rights and Legal Systems: Empirical Influence on Economic Behavior
Property rights and legal frameworks establish the rules governing ownership, exchange, and dispute resolution, directly shaping incentives for investment, innovation, and compliance. Below are case studies illustrating their transformative effects:
-
Land Reform and Agricultural Productivity
The Mexican Ejido System (1917–1992) redistributed land to collective ownership but stifled productivity due to fragmented incentives. Post-reform privatization (1992) increased yields by ~20% (World Bank, 2005) as farmers gained exclusive rights to manage land. Conversely, Zimbabwe’s Fast-Track Land Reform (2000) disrupted commercial agriculture, reducing output by ~50% due to insecure tenure and lack of credit access.
-
Intellectual Property and Technological Diffusion
India’s patent law reforms (2005) aligned with TRIPS Agreement, boosting pharmaceutical R&D. However, South Africa’s AIDS crisis highlighted the tension between patent monopolies (e.g., Merck’s HIV drug pricing) and public health access, resolved via compulsory licensing. In contrast, China’s "Made in China 2025" strategy leveraged weak IP enforcement to accelerate tech transfer, though it sparked trade conflicts (e.g., U.S. tariffs on Chinese solar panels).
-
Contract Enforcement and Foreign Direct Investment (FDI)
Singapore’s legal system—ranked #1 in the World Bank’s Doing Business (2020)—attracts ~20% of FDI in Southeast Asia due to predictable contract enforcement. Conversely, Venezuela’s expropriations (e.g., oil industry nationalizations) deterred investment, contributing to a 75% GDP contraction (2013–2019) (IMF).
-
Common Property Resources and Sustainability
Elinor Ostrom’s Nobel-winning research on Swiss alpine pastures showed that decentralized governance (shared rules, monitoring) sustained grazing resources without state or private ownership. In contrast, overfishing in the North Atlantic (pre-2010 quotas) depleted stocks by
Economics is more than a study of money or markets; it is the science of human behavior under constraints, offering frameworks to decode everything from personal spending habits to national policy failures. By distinguishing between microeconomic interactions—where supply and demand dictate prices—and macroeconomic forces like inflation and unemployment, the discipline equips analysts with tools to assess trade-offs between efficiency and equity. Historical shifts, from the Industrial Revolution to the rise of behavioral insights, underscore economics’ dynamic nature, while contemporary models grapple with sustainability and inequality. Ultimately, economics does not merely explain the past but empowers societies to design systems that balance prosperity with fairness, proving its enduring relevance in an era of rapid change.
FAQ
define what is home economics?
Q: What exactly is home economics and how does it differ from general economics?
explain what is economics?
Q: How would you explain economics in simple terms?
define utility is economics?
Q: What does the term "utility" mean in the context of economics?
define economics class 11?
Q: What is the definition of economics as taught in Class 11 curriculum?
define economics according to adam smith?
Q: How did Adam Smith define economics, and what were his key ideas?
define economics according to lionel robbins?
Q: What is Lionel Robbins' definition of economics, and why is it important?
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Voltefac.