What Is Taxable Salary Explained Clearly And Comprehensively

Published

Table of Contents

Understanding what constitutes taxable salary is essential for employees, employers, and tax professionals navigating financial obligations and compliance requirements. Taxable salary encompasses more than just base pay—it includes allowances, bonuses, and other compensations subject to taxation under specific legal frameworks, while excluding certain exemptions and fringe benefits. Misclassification of components can lead to discrepancies in tax filings, audits, or financial penalties, underscoring the need for precise definitions and regional distinctions. This guide dissects the core elements of taxable salary, contrasts taxable and non-taxable components, and examines jurisdictional variations to ensure clarity and accuracy in financial planning.

The distinction between taxable and non-taxable income is not always straightforward, as it hinges on regulatory nuances, employer policies, and individual circumstances. For instance, while housing or transport allowances may be tax-exempt in one country, they could be fully taxable in another. Similarly, fringe benefits like company cars or meal vouchers may incur tax liabilities under specific conditions, complicating payroll administration. By exploring real-world examples, legal precedents, and calculation methodologies, this discussion equips stakeholders with the tools to optimize tax efficiency while maintaining full compliance with evolving tax laws.

what is taxable salary

Definition and Core Components of Taxable Salary

Taxable salary refers to the portion of an employee’s compensation subject to income tax as defined by regulatory authorities. It encompasses remuneration elements that meet legal criteria for taxation, excluding exemptions or non-taxable benefits. Understanding these components is essential for accurate tax compliance, payroll processing, and financial planning. This section examines the fundamental elements of taxable salary, including base pay, allowances, and statutory deductions, while distinguishing between taxable and non-taxable items through structured comparisons.

Fundamental Elements of Taxable Salary

Taxable salary is composed of core remuneration components that regulatory frameworks classify as taxable income. These elements typically include:

Base Pay
The foundational component of taxable salary, base pay represents the fixed compensation an employee receives for their role, excluding additional benefits or variable payments. It is the most consistent and predictable element of taxable income, forming the baseline for tax calculations.

Allowances and Perquisites
Allowances such as housing, transport, or meal allowances may be taxable depending on their nature and regulatory definitions. For instance, some jurisdictions tax allowances exceeding a specified threshold, while others exempt them entirely. Perquisites (e.g., company-provided vehicles or accommodation) are often subject to tax unless explicitly excluded by law.

Variable Compensation
Bonuses, commissions, and profit-sharing are typically taxable as they constitute additional income. These components are added to the base salary to determine the total taxable income, unless specific exemptions apply under local tax codes.

Statutory Deductions and Contributions
While deductions such as social security or pension contributions reduce net pay, they do not directly affect taxable salary. However, employer-matched contributions (e.g., to retirement funds) may be taxable if classified as taxable fringe benefits under certain jurisdictions.

Structured Breakdown of Taxable Income Components

The distinction between gross salary, taxable income, and non-taxable perks is critical for accurate tax reporting. Below is a comparative table summarizing these components under common regulatory frameworks (e.g., IRS, local tax authorities):
Category Taxable Items Non-Taxable Items (Common Exemptions) Regulatory Basis (Examples)
Base Compensation Basic salary N/A IRS Section 61(a)(1), most local tax laws
Overtime pay N/A IRS Section 61(a)(1), Fair Labor Standards Act (FLSA)
Severance pay (unless exempt) Exempt if part of a legally required termination package (e.g., some EU jurisdictions) IRS Revenue Ruling 74-344, local labor codes
Commissions and bonuses N/A IRS Section 61(a)(1)
Allowances Housing allowance (above statutory limits) Housing allowance up to IRS/HUD limits (e.g., $50,000 in high-cost areas) IRS Publication 521, local housing subsidies
Transport allowance (if exceeds standard rates) Standard transport reimbursement (e.g., $0.55/mile in the U.S.) IRS Revenue Procedure 2019-47, local transit subsidies
Meal allowance (if not job-related) De minimis meal allowances (e.g., <$50/month) IRS Notice 2011-70, local de minimis rules
Perquisites Company-provided car (personal use) Company-provided car (business-only use) IRS Section 1.61-2(a), local fringe benefit codes
Gym memberships (personal use) Gym memberships for employee wellness programs (limited scope) IRS Notice 2002-11, local wellness incentives
Variable Compensation Stock options (upon exercise) N/A (unless employer stock purchase plans qualify) IRS Section 83, local capital gains rules
Profit-sharing distributions N/A IRS Section 401(k) plans (if tax-deferred)
Key Notes:
  • Taxable Income Calculation: Gross salary minus non-taxable allowances/perks equals taxable income.
  • Jurisdictional Variations: Exemptions differ by country/state (e.g., Canada’s Employment Insurance vs. U.S. FICA).
  • Documentation Requirements: Employers must maintain records to substantiate taxable/non-taxable classifications (e.g., IRS Form W-4, local payroll registers).
  • Taxable salary is governed by statutory and administrative guidelines that vary by jurisdiction. Below are key frameworks and their defining clauses:

    United States (IRS)

  • Internal Revenue Code (IRC) Section 61(a)(1): Broadly defines gross income as "all income from whatever source derived," including salaries, wages, and bonuses.
  • IRC Section 105: Exempts employer-provided accident/health benefits from taxation if paid directly to providers.
  • IRC Section 132: Outlines de minimis fringe benefits (e.g., holiday gifts, occasional meals) that may be non-taxable.
  • Publication 15-B: Provides employer guidelines for withholding taxes on various compensation types.
  • European Union (Example: Germany)

  • Income Tax Act (EStG) § 19: Classifies employment income (Arbeitslohn) as taxable, excluding statutory allowances (e.g., Wohnungszuschuss up to €1,000/month).
  • Social Security Code (SGB IV): Defines contribution bases for social security taxes, which may differ from income tax thresholds.
  • Double Taxation Agreements: Modify taxability for cross-border employees (e.g., Article 15 OECD Model Tax Convention).
  • India (Income Tax Act, 1961)

  • Section 17(1): Taxes salary income, including basic pay, allowances (unless exempt under Section 10), and perquisites (Section 17(2)).
  • Section 10(14): Exempts House Rent Allowance (HRA) up to 50% of basic salary (40% in metros).
  • Rule 3: Specifies valuation methods for perquisites (e.g., 10% of salary for company cars).
  • Australia (Taxation Act 1997)

  • Section 6-5: Defines assessable income, including salaries, wages, and allowances (unless specifically excluded).
  • Section 11-10: Exempts certain fringe benefits (e.g., work-related items under the FBT exemption).
  • Taxation Ruling TR 93/16: Clarifies tax treatment of allowances and reimbursements.
  • Blockquote: Taxable Income Formula

    Taxable Salary = Gross Salary – Non-Taxable Allowances/Perks + Taxable Fringe Benefits
    Regulatory Citations for Employers:
  • Maintain payroll records for 4+ years (U.S. IRS) or as per local statutes.
  • File Form W-2 (U.S.) or equivalent (e.g., P60 in the UK, Form 16 in India) to report taxable income.
  • Adhere to withholding obligations (e.g., U.S. Form 941
  • Taxable vs. Non-Taxable Salary Components

    Understanding the distinction between taxable and non-taxable salary components is critical for accurate payroll processing, tax compliance, and employee compensation planning. Taxable salary elements directly impact an individual’s taxable income, influencing their income tax liability, social security contributions, and other statutory deductions. Conversely, non-taxable components reduce the overall tax burden without affecting the employee’s gross income calculation. Misclassification of these components can lead to regulatory penalties, disputes with tax authorities, or unintended financial consequences for both employers and employees. This section systematically categorizes common salary elements, clarifies their tax treatment, and outlines the conditions under which fringe benefits may become taxable under prevailing tax laws.

    Classification of Taxable and Non-Taxable Salary Components

    Taxable salary components are those that contribute to an employee’s gross taxable income, subjecting them to income tax, payroll taxes, and other statutory levies. Non-taxable components, while part of the employee’s compensation package, are excluded from taxable income under specific legal provisions. Below is a comparative breakdown of these categories, including illustrative examples and contextual explanations.

    Taxable Salary Components
    Taxable components are defined by their direct correlation to an employee’s economic benefit derived from employment. These typically include:

    • Base Salary and Wages
      The fixed or variable remuneration agreed upon in an employment contract, including hourly wages, monthly salaries, and annual compensation.
      Example: A monthly salary of $5,000 paid to a full-time employee is fully taxable.
    • Bonuses and Incentives
      Performance-based payments, including annual bonuses, profit-sharing, and signing bonuses, are generally taxable unless explicitly excluded by law.
      Example: A year-end bonus of $2,000 awarded for exceeding sales targets is taxable income.
    • Commissions and Overtime Pay
      Earnings derived from sales performance or additional hours worked are fully taxable, as they represent direct compensation for services rendered.
      Example: A 10% commission on sales exceeding $50,000 is taxable as part of the employee’s gross income.
    • Allowances with Monetary Value
      Certain allowances, such as housing allowances, car allowances, or education allowances, may be taxable if they exceed statutory exemptions or lack substantiation as reimbursements.
      Example: A $1,500 monthly housing allowance provided without proof of actual rent payments may be taxable.
    • Stock Options and Equity Compensation
      Employer-provided stock options, restricted stock units (RSUs), or employee stock purchase plans (ESPPs) are typically taxable upon vesting or exercise, depending on the jurisdiction’s tax treatment.
      Example: The fair market value of vested stock options exercised at $30 per share (when granted at $20) triggers a taxable benefit of $10 per share.
    • Relocation and Moving Expenses
      Reimbursements or advances for relocation costs may be taxable if they exceed de minimis thresholds or lack documentation as bona fide business expenses.
      Example: A lump-sum relocation payment of $10,000 without proof of actual moving costs may be fully taxable.
    Non-Taxable Salary Components
    Non-taxable components are excluded from taxable income under specific legal frameworks, such as exemptions, deductions, or fringe benefit provisions. These often serve as incentives for employers to offer additional benefits without increasing the employee’s tax liability.
    • Reimbursements for Business Expenses
      Amounts reimbursed to employees for documented business-related expenses, provided they are substantiated and comply with accounting principles.
      Example: Reimbursement of $400 for business travel tickets with original receipts is non-taxable.
    • Scholarships and Educational Grants
      Funds provided by employers for educational purposes, including tuition fees, books, or supplies, may be non-taxable if they meet the criteria of an educational scholarship under tax law.
      Example: A $5,000 annual scholarship for an employee pursuing a master’s degree, provided the funds are used exclusively for education.
    • De Minimis Fringe Benefits
      Small, infrequent benefits provided by employers that do not have a monetary value, such as occasional meals, holiday gifts, or nominal awards.
      Example: A $25 gift card for an employee’s birthday is non-taxable as a de minimis benefit.
    • Health Insurance and Medical Benefits
      Employer-sponsored health insurance premiums, medical reimbursement accounts (MRAs), and certain wellness programs are typically non-taxable under tax-exempt provisions.
      Example: Contributions of $1,200 monthly toward an employee’s health insurance premium are non-taxable.
    • Retirement Contributions
      Employer contributions to qualified retirement plans, such as 401(k)s or pension funds, are non-taxable until distributed, as they are deferred from taxable income.
      Example: A $1,000 monthly contribution by the employer to an employee’s 401(k) plan is non-taxable.
    • Certain Transportation Benefits
      Employer-provided transit passes, parking allowances (up to statutory limits), or vanpooling benefits may be non-taxable if they comply with IRS or local tax regulations.
      Example: A monthly transit pass valued at $130 (2023 IRS limit) provided by the employer is non-taxable.

    Tax Treatment of Fringe Benefits

    Fringe benefits are additional perks or services provided by employers beyond standard salary or wages. Their taxability depends on their nature, value, and compliance with statutory exemptions. Below are key categories of fringe benefits and their classification under tax laws, along with conditions that may render them taxable.

    Common Fringe Benefits and Their Tax Classification
    Fringe benefits can be categorized based on their tax treatment, ranging from fully taxable to entirely exempt. The following table summarizes their classification and applicable conditions:

    Fringe Benefit Type Taxable Status Conditions for Non-Taxability Example
    Company Cars (Personal Use) Taxable
    • Excluded if used primarily for business purposes (e.g., >50% business use).
    • Taxable based on the lease value or fair market value minus business-use percentage.
    A company-provided sedan used 30% for business and 70% for personal use triggers taxable income based on the 70% personal-use value.
    Meal Vouchers or Dining Allowances Partially Taxable
    • Non-taxable up to statutory limits (e.g., $5/day for meals under IRS Section 132(f)).
    • Excess amounts over the limit are taxable.
    A $6 daily meal voucher includes $1 of taxable income (exceeding the $5 limit).
    Gym Memberships or Wellness Programs Non-Taxable (De Minimis)
    • Must be provided on a non-discriminatory basis.
    • Value must not exceed $50/month per employee.
    A $40/month gym membership provided by the employer is non-taxable.
    Housing Allowances Taxable or Non-Taxable
    • Non-taxable if reimbursed for actual housing costs (with documentation).
    • <

      what is taxable salary - Ilustrasi 2

      Regional and Jurisdictional Variations in Taxable Salary Definitions

      Taxable salary structures vary significantly across global jurisdictions due to differences in tax laws, labor regulations, and economic policies. These variations influence how employers classify compensation, how employees report income, and the overall tax burden on individuals. Understanding these regional distinctions is critical for multinational corporations, expatriates, remote workers, and freelancers navigating cross-border employment. Jurisdictional differences may arise from variations in tax treaties, social security contributions, deductions, and the treatment of fringe benefits, all of which directly impact the calculation of taxable income.

      The following sections analyze how taxable salary definitions diverge across key regions, including the U.S. federal and state systems, EU member states, and Asian tax regimes, with a focus on practical implications for different employment categories.

      Key Regional Differences in Taxable Salary Definitions

      Taxable salary definitions are shaped by legal frameworks that prioritize different economic or social objectives. For example, some jurisdictions emphasize gross income inclusivity (e.g., all cash and non-cash compensation), while others allow exemptions for specific benefits (e.g., housing allowances, education stipends). Below is a comparative table summarizing core differences across major regions, highlighting variations in taxable components, deductions, and reporting requirements.
      Region/Jurisdiction Taxable Components Non-Taxable Exemptions Deductions Allowed Social Security Contributions Tax Filing Requirements
      U.S. (Federal)
      • Wages, salaries, bonuses, commissions.
      • Non-cash benefits (e.g., company cars, stock options, relocation expenses).
      • Certain fringe benefits (e.g., health insurance premiums paid by employer, up to IRS limits).
      • Qualified retirement contributions (e.g., 401(k), IRA).
      • Health Savings Accounts (HSAs).
      • Dependent care assistance (up to $5,000/year).
      • Standard deduction or itemized deductions (e.g., mortgage interest, charitable contributions).
      • State-specific deductions (e.g., California’s education incentives).
      • Social Security (6.2% employee + 6.2% employer).
      • Medicare (1.45% employee + 1.45% employer).
      • W-2 forms for employees; 1099 for contractors.
      • Annual federal and state filings (deadlines vary by state).
      EU (Member States)
      • Base salary, overtime, bonuses, and allowances (e.g., mobility allowances in Germany).
      • Non-cash benefits (e.g., company-provided housing in France).
      • Pension contributions (e.g., 4%–12% of salary in Netherlands).
      • Health insurance premiums (mandatory in most EU states).
      • Education stipends (e.g., tax-free in Sweden for certain programs).
      • Work-related expenses (e.g., 20% flat deduction in Belgium).
      • Childcare allowances (e.g., €100/month in Germany).
      • Social security contributions vary (e.g., ~22% in France, ~15% in Estonia).
      • Employer and employee split (e.g., 50/50 in Sweden).
      • Annual tax returns (e.g., Form P60 in UK, Aanvullende Inkomstenbelasting in Netherlands).
      • Employer withholding (e.g., PAYE in UK, Prélèvement à la source in France).
      Asia (Singapore, Japan, India)
      • Basic salary, allowances (e.g., housing in Singapore), and bonuses.
      • Non-cash perks (e.g., company-provided meals in Japan).
      • CPF contributions (Singapore: up to ~20% of salary).
      • Education scholarships (India: tax-free under Section 10(14)).
      • Relocation expenses (Japan: tax-exempt for certain expatriates).
      • Standard deductions (e.g., ₹50,000 in India).
      • Home loan interest (Singapore: up to S$35,000/year).
      • CPF (Singapore: ~20% employee + ~17% employer).
      • Pension funds (Japan: ~18.3% total).
      • Provident Fund (India: ~12% employee + ~12% employer).
      • Annual returns (e.g., Form 24 in Singapore, Kakutei Shinkoku in Japan).
      • Employer reporting (e.g., Form 16 in India).
      Key Observations:
    • Inclusivity vs. Exclusivity: The U.S. and EU tend to include broader compensation components (e.g., stock options, relocation) in taxable income, while Asian jurisdictions often exclude specific allowances (e.g., housing, education) if tied to policy objectives.
    • Social Security Contributions: EU systems frequently split contributions between employers and employees, whereas Asian regimes (e.g., Singapore’s CPF) may consolidate them under mandatory savings schemes.
    • Deductions: EU countries offer work-related expense deductions, while the U.S. focuses on standard/itemized deductions. Asian jurisdictions like India provide sector-specific exemptions (e.g., agricultural income).
    • Case Studies: Taxable Salary in High-Tax vs. Low-Tax Jurisdictions

      The treatment of taxable salary in high-tax and low-tax jurisdictions reflects broader economic strategies, such as attracting talent or stimulating local industries. Below are real-world examples illustrating how expatriate packages, remote work, and freelance income are taxed differently.

      1. Expatriate Packages in High-Tax vs. Low-Tax Regions

    • High-Tax Jurisdiction (France):
    • An expatriate earning €120,000/year in Paris may receive a taxable salary including:
    • Base salary (€100,000).
    • Mobility allowance (€10,000) – partially taxable unless tied to relocation costs.
    • Housing benefit (€10,000) – fully taxable unless provided by the employer as a tax-exempt benefit under local law.
    • Pension contributions (€12,000) – deducted from taxable income.
    • Effective Tax Rate: ~45% (including income tax + social charges), with deductions reducing the base by ~20%.

      - Low-Tax Jurisdiction (Singapore):
      The same expatriate earning

      Deductions and Adjustments Affecting Taxable Salary

      Taxable salary is not merely the gross compensation received by an employee but is subject to adjustments through deductions and post-tax modifications. These adjustments play a critical role in determining the final taxable income, influencing both employer and employee tax obligations. Pre-tax deductions reduce the salary before taxation, while post-tax adjustments, such as credits and exemptions, further mitigate tax liability after gross income is assessed. Understanding these mechanisms is essential for accurate tax planning, compliance, and optimizing financial outcomes.

      The application of deductions and adjustments varies by jurisdiction, with specific limits, eligibility criteria, and procedural requirements. Below, the distinction between pre-tax and post-tax adjustments is examined, followed by a structured methodology for calculating net taxable salary.

      Pre-Tax Deductions Reducing Taxable Income

      Pre-tax deductions are voluntary or mandatory contributions subtracted from an employee’s gross salary before income tax is calculated. These deductions lower the taxable income, thereby reducing taxable liability. Common examples include retirement contributions (e.g., 401(k), 403(b)), health insurance premiums, and dependent care expenses. The eligibility and contribution limits for these deductions are governed by tax codes and employer policies.

      Employers typically facilitate pre-tax deductions through payroll systems, where employees designate the percentage or fixed amount to be withheld. For instance, a 401(k) contribution reduces taxable income up to the annual limit set by the Internal Revenue Service (IRS) or equivalent regional authority. In 2023, the IRS limit for 401(k) employee contributions was $22,500, with an additional $7,500 catch-up contribution for individuals aged 50 or older.

      Key considerations for pre-tax deductions include:

    • Eligibility: Employees must meet employer-specific criteria (e.g., tenure requirements for retirement plans).
    • Contribution Limits: Annual caps apply to deductions (e.g., health savings accounts (HSAs) have a family limit of $7,750 for 2023).
    • Tax Implications: Deductions reduce taxable income but may affect eligibility for certain tax credits (e.g., the Earned Income Tax Credit).
    • Post-Tax Adjustments Mitigating Tax Liability

      Post-tax adjustments do not directly reduce gross salary but modify taxable income after deductions have been applied. These include tax credits (e.g., Child Tax Credit, Education Credits), exemptions (e.g., personal or dependency exemptions), and deductions (e.g., standard or itemized deductions). Unlike pre-tax deductions, post-tax adjustments are claimed on tax returns and may require substantiation through documentation.

      For example, the Child Tax Credit (CTC) in the U.S. provides up to $2,000 per qualifying child, with partial refundability for lower-income earners. In 2023, a taxpayer with two children could reduce their tax liability by $4,000, assuming eligibility. This credit directly offsets tax owed rather than reducing taxable income.

      > Real-World Example:
      > A taxpayer with a gross salary of $80,000 and pre-tax deductions of $10,000 (e.g., 401(k) and health insurance) has a taxable income of $70,000. If they qualify for a $3,000 standard deduction and a $1,500 education credit, their net taxable income for liability purposes is $65,500, resulting in a lower tax burden compared to gross income.

      Post-tax adjustments are subject to:

    • Income Thresholds: Credits or exemptions may phase out at higher income levels (e.g., the CTC reduces for single filers earning over $200,000).
    • Documentation Requirements: Credits like the Earned Income Tax Credit (EITC) require proof of earned income and dependents.
    • Regional Variations: Some jurisdictions offer additional credits (e.g., state-level childcare credits).
    • Step-by-Step Procedure for Calculating Net Taxable Salary

      Calculating net taxable salary involves systematically applying pre-tax deductions and post-tax adjustments. Below is a structured approach using formulas and examples:

      1. Determine Gross Salary

    • Sum all taxable compensation, including base salary, bonuses, and commissions.
    • Formula:
    • Gross Salary = Base Salary + Bonuses + Commissions + Other Taxable Benefits

      2. Apply Pre-Tax Deductions

    • Subtract eligible pre-tax contributions (e.g., retirement, insurance).
    • Formula:
    • Taxable Income Before Adjustments = Gross Salary – (401(k) Contributions + Health Insurance + Other Pre-Tax Deductions)
    • Example: If gross salary is $75,000 and pre-tax deductions total $8,000, taxable income before adjustments is $67,000.
    • 3. Subtract Standard or Itemized Deductions

    • Choose between the standard deduction (e.g., $13,850 for single filers in 2023) or itemized deductions (e.g., mortgage interest, charitable donations).
    • Formula:
    • Adjusted Taxable Income = Taxable Income Before Adjustments – (Standard Deduction OR Itemized Deductions)

      4. Apply Tax Credits

    • Reduce tax liability directly using eligible credits (e.g., CTC, EITC).
    • Formula:
    • Net Taxable Income = Adjusted Taxable Income – (Tax Credits + Exemptions)
    • Example: With a $3,000 education credit, net taxable income becomes $64,000 (assuming no exemptions).
    • 5. Calculate Tax Liability

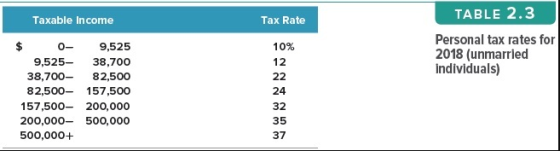
    • Apply the progressive tax rate to net taxable income.
    • Formula:
    • Tax Liability = (Net Taxable Income × Applicable Tax Rate) – Tax Credits
    • Note: Regional tax tables (e.g., federal, state, local) determine rates.
    • Step Action Formula
      1 Gross Salary Calculation Base + Bonuses + Commissions
      2 Pre-Tax Deductions Gross – (401(k) + Insurance + Others)
      3 Deductions (Standard/Itemized) Taxable Income – Deductions
      4 Tax Credits/Exemptions Adjusted Income – Credits
      5 Tax Liability (Net Taxable Income × Rate) – Credits

      what is taxable salary - Ilustrasi 3

      Common Misconceptions and Clarifications on Taxable Salary

      Taxable salary is a critical concept in payroll and tax compliance, yet misunderstandings persist due to evolving regulations, regional variations, and employer misinterpretations. Many employees and employers incorrectly classify salary components, leading to unintended tax liabilities, audits, or financial penalties. This section addresses prevalent myths, provides evidence-based corrections, and highlights real-world consequences of misclassification. Illustrative examples demonstrate how incorrect assumptions—such as treating allowances as universally non-taxable or assuming overtime is always exempt—can result in compliance risks.

      Debunking Myths About Taxable and Non-Taxable Salary Components

      Misconceptions often arise from oversimplifications of tax laws, outdated guidance, or industry-specific practices. Below are common fallacies, their factual corrections, and supporting evidence from tax authorities and legal precedents.

      Myth 1: Overtime Pay is Always Non-Taxable
      Clarification: Overtime pay is taxable income under most jurisdictions, including the U.S. (IRS), Canada (CRA), and the EU (directive 2011/16/EU). The taxability depends on the type of overtime (e.g., statutory vs. voluntary) and local laws, but exemptions are rare and typically tied to specific conditions (e.g., certain public sector roles or collective bargaining agreements).
      Evidence:

    • U.S. IRS (Publication 15-T): "All wages paid to employees are subject to federal income tax withholding unless exempt."
    • UK HMRC: Overtime is taxable unless part of a tax-free allowance (e.g., under a HMRC-approved scheme like the "Trivial Benefits" rule, capped at £50 per item).
    • Consequence: Employers failing to withhold taxes on overtime may face back taxes, penalties (e.g., 10%–40% of unpaid tax under IRS Section 6651), and interest charges.

      Example of Misclassification:
      A retail manager in California was paid $1,200/month in overtime without tax withholding, assuming it was a "bonus." During an audit, the IRS reclassified it as taxable income, resulting in:

    • $300 in unpaid federal income tax (22% bracket).
    • $200 in penalties (failure-to-withhold).
    • Employer liability for employer share of payroll taxes (7.65% FICA).
    • Allowances: Tax-Free by Default or Exception?

      The assumption that all allowances are non-taxable is incorrect. Taxability depends on jurisdiction, purpose, and employer intent. Below are key distinctions:

      Taxable Allowances (Common Misconceptions):

    • Housing Allowances (if not HMRC-approved in the UK or IRS Section 119 in the U.S.).
    • Example: A U.S. employer provides a $1,500/month housing allowance but does not meet IRS Section 119 criteria (e.g., no imputed income or actual expense documentation). The full amount is taxable.
    • Car Allowances (unless under a tax-advantaged scheme like the UK’s Company Car Tax or U.S. Fringe Benefit Rule).
    • Example: A German employee receives a €800/month car allowance but uses it for personal travel. Under §38 EStG, this is taxable unless part of a tax-free business expense reimbursement.
    • Education Allowances (if not tied to employer-mandated training).
    • Example: A tech firm in Singapore pays S$2,000/year for employee courses, but the courses are unrelated to job requirements. Under Section 13(1)(a) of the Income Tax Act, this is taxable as a benefit-in-kind.

      Non-Taxable Allowances (With Conditions):

    • Relocation Allowances (if documented as reimbursement for qualifying expenses).
    • Example: A multinational employer in the UAE reimburses an employee’s AED 50,000 moving costs with proof of invoices. Under Federal Tax Law No. 47 of 1997, this is non-taxable.
    • Meals on Duty (if substantiated and under local limits).
    • Example: A U.S. police officer receives $25/day for meals during overnight shifts, documented in a log. Under IRS Revenue Ruling 2005-74, this is non-taxable if ordinary and necessary.

      Consequence of Misclassification: A UK employer provided £3,000/year in "unrestricted allowances" to employees, claiming they were non-taxable. HMRC audited the company and reassessed:

    • £1,200 in unpaid income tax per employee (40% tax bracket).
    • £300 in penalties per employee (failure to operate PAYE correctly).
    • Employer NICs liability (13.8% on the misclassified amount).
    • FAQ: Clarifying Taxable Salary Queries

      Below is a structured table addressing frequent inquiries about taxable salary components, based on global tax authority guidance and case law.
      Question Clarification
      Are bonuses always taxable?

      Bonuses are taxable unless explicitly exempt by law. Examples of non-taxable bonuses include:

      • UK: Trivial Benefits (£50 or less per item, not cash).
        HMRC Example: A £40 gift card for an employee’s birthday is non-taxable.
      • U.S.: De minimis fringe benefits (e.g., occasional meals under $25).
        IRS Example: A $20 holiday turkey gift is non-taxable if infrequent.
      • Singapore: Approved performance bonuses under the Employment Income Act (e.g., productivity-linked bonuses capped at 20% of salary).

      Risk: Employers misclassifying bonuses as "gifts" or "reimbursements" may face back taxes and penalties (e.g., 20% underpayment penalty in the U.S.).

      Is stock compensation (e.g., RSUs) always taxable?

      Stock compensation is taxable at vesting or exercise, but timing and treatment vary:

      • U.S. (IRS §83): Taxed as ordinary income at fair market value (FMV) when vested, unless an ISO (Incentive Stock Option) qualifies for capital gains treatment.
      • EU (Directive 2003/48/EC): Taxed as benefits in kind at FMV, with member-state variations (e.g., France taxes at 50% of FMV).
      • Example of Misclassification: A tech company in the Netherlands granted €50,000 in RSUs but did not withhold taxes at vesting. The Dutch tax authority reassessed:
      Consequence: €12,500 in unpaid income tax (25% rate) + €2,500 in penalties (20% of tax due).
      Are reimbursements for business expenses always non-taxable?

      Reimbursements are non-taxable only if:

      • Substantiated by receipts/invoices.
      • Directly related to employment.
      • Paid under an accountable plan (U.S.) or expense reimbursement scheme (UK/EU).

      Red Flags for Taxable Reimbursements:

      • Lump-sum payments without documentation (

        Tools and Methods for Calculating Taxable Salary

        Accurate calculation of taxable salary is essential for compliance with tax regulations, employee payroll transparency, and financial planning. Organizations and individuals rely on a combination of automated tools, manual methods, and professional guidance to ensure precision. Payroll software systems, spreadsheet templates, and tax calculators streamline the process while accounting for regional variations, deductions, and statutory adjustments. Below are structured approaches for calculating taxable salary, including software automation, manual methodologies, and verification techniques.

        Automated Payroll Software for Taxable Salary Calculation

        Payroll software integrates tax laws, regional compliance rules, and deduction structures to automate taxable salary computations. Platforms like ADP Workforce Now, QuickBooks Payroll, Gust, and Sage Payroll offer features tailored to jurisdictional requirements, reducing manual errors and ensuring real-time adjustments for tax code updates.

        Key Features of Payroll Software for Taxable Salary:

      • Regional Tax Tables Integration: Preloaded databases for federal, state, and local tax rates, including variations like California’s payroll taxes, New York City’s additional municipal tax, or Texas’ franchise tax.
      • Automatic Deduction Handling: Deductions for 401(k) contributions, health insurance premiums, garnishments, and FICA taxes are applied dynamically, adjusting taxable income accordingly.
      • Multi-State Payroll Support: Tools like ADP and Paychex accommodate employees working across state lines, applying the correct tax withholding based on nexus rules and reciprocal agreements (e.g., between Pennsylvania and New Jersey).
      • Year-to-Date (YTD) Tracking: Software maintains cumulative records of taxable earnings, ensuring accurate W-2 reporting and quarterly tax filings.
      • Compliance Alerts: Notifications for changes in tax laws (e.g., IRS Publication 15 updates) or regional mandates (e.g., San Francisco’s paid sick leave tax).
      • Example Workflow in ADP Workforce Now:
        1. Employee Data Input: Gross salary, job location (city/state), and benefit elections (e.g., HSA contributions).
        2. Tax Layer Application: System applies federal withholding (using IRS Publication 15-T), state withholding (e.g., California DE 4 tax tables), and local taxes (if applicable).
        3. Deduction Processing: Adjusts taxable income for pre-tax benefits (e.g., FSA) and post-tax deductions (e.g., union dues).
        4. Net Pay Calculation: Displays taxable salary alongside net take-home pay, with itemized breakdowns for audit trails.

        Limitations to Consider:

      • Software Updates: Delays in incorporating new tax legislation may require manual overrides.
      • Custom Deductions: Unique employer-provided benefits (e.g., relocation stipends) may not be pre-coded and require manual adjustments.
      • International Payroll: Software like Deel or Rippling handles global taxable salary calculations but may lack granularity for niche regional rules.
      • Manual Calculation Templates for Taxable Salary

        For small businesses, freelancers, or scenarios where payroll software is unavailable, spreadsheet-based templates provide a structured method for calculating taxable salary. Below is a sample template (described in text format) with embedded formulas, adaptable to Excel or Google Sheets.

        Template Structure:

        ColumnDescriptionFormula/Example
        A: Employee NameIdentifier for payroll records.Text input (e.g., "John Doe").
        B: Gross SalaryTotal earnings before deductions (e.g., hourly wages, bonuses, commissions).Numerical input (e.g., $5,000/month).
        C: Pre-Tax DeductionsItems reducing taxable income (e.g., 401(k), HSA, FSA).Sum of values (e.g., `=SUM(D2:D10)`).
        D: Taxable IncomeGross salary minus pre-tax deductions.`=B2 - C2` (e.g., $5,000 - $1,200 = $3,800).
        E: Federal WithholdingCalculated using IRS Percentage Method Tables or Wage Bracket Method.Lookup table or formula (e.g., `=VLOOKUP(D2, FederalTaxTable, 2, FALSE)`).
        F: State TaxApplied based on state-specific rates (e.g., California’s 1–13.3% progressive tax).`=D2 StateTaxRate` (e.g., `=D2 0.06` for 6% flat rate).
        G: Local TaxIncludes city/county taxes (e.g., New York City’s 3.8765% rate).`=D2 LocalTaxRate` (e.g., `=D2 0.038765`).
        H: FICA TaxesSocial Security (6.2%) + Medicare (1.45%).`=(D2 0.062) + (D2 0.0145)`.
        I: Net Taxable PayTaxable income after all withholdings.`=D2 - (E2 + F2 + G2 + H2)`.
        J: Net Take-Home PayFinal amount after post-tax deductions (e.g., health insurance, garnishments).`=I2 - SUM(K2:K10)` (where K2:K10 lists post-tax deductions).
        Key Formulas and References:
      • Federal Withholding: Use the IRS Publication 15-T tables or the IRS Withholding Calculator for precise calculations. For example:
      • Federal Taxable Wage Formula (Simplified):
        `Taxable Wages = Gross Wages – Pre-Tax Deductions – Standard Deduction (if applicable)`
      • State-Specific Adjustments: States like Texas (no state income tax) or Washington (no state tax) require zero entries in the state tax column.
      • Local Tax Nuances: Cities like Philadelphia impose an additional 3.894% wage tax, which must be added to the local tax column.
      • Example Calculation (California Resident):

        ItemAmount
        Gross Salary$6,500
        Pre-Tax 401(k)-$1,000
        Taxable Income$5,500
        Federal Withholding-$650
        California State Tax-$385
        Local Tax (e.g., LA)-$210
        FICA Taxes-$423.50
        Net Taxable Pay$4,031.50
        Post-Tax Health Ins.-$300
        Net Take-Home Pay$3,731.50
        Template Customization Tips:
      • Conditional Formatting: Highlight cells requiring manual input (e.g., state-specific rates).
      • Data Validation: Restrict dropdowns for states/cities to pre-populated lists to avoid errors.
      • Macros for Recurring Tasks: Automate quarterly tax adjustments or year-end reporting.
      • Consulting Tax Professionals and Online Calculators

        While software and templates streamline calculations, tax professionals and official calculators provide validation and expertise for complex scenarios. Below are structured methods for leveraging these resources.

        1. IRS Withholding Calculator
        The IRS Tax Withholding Estimator (https://www.irs.gov/individuals/tax-withholding-estimator) is a free tool for verifying federal taxable salary calculations. Steps for accurate input:

      • Step 1: Input Personal Information
      • Enter filing status (Single, Married, etc.), number of dependents, and expected deductions (e.g., student loan interest).
      • Step 2: Enter Pay and Deductions
      • Specify annual pay, frequency (weekly, biweekly), and pre-tax deductions (e.g., 403(b) contributions

        Determining what is taxable salary requires a structured approach that balances legal precision with practical application. From dissecting gross salary components to navigating regional tax regimes, the process demands attention to detail—whether through automated payroll systems, manual calculations, or professional consultations. Employers must design compensation packages that align with tax obligations, while employees should verify their taxable income to avoid surprises during filings. As tax landscapes evolve, staying informed about deductions, exemptions, and jurisdictional differences remains critical. This guide serves as a foundational resource, demystifying taxable salary to foster transparency, compliance, and financial clarity for all parties involved.

        FAQ

        What exactly constitutes taxable salary in India, and how is it calculated?

        In India, taxable salary includes basic pay, allowances (except exempt ones like HRA, LTA, or medical), bonuses, and perquisites (e.g., company car, housing). Deductions like standard deduction (₹50,000), NPS, or HRA (if applicable) reduce taxable income. Tax is applied based on the slab rates after deductions under the Income Tax Act.

        How is taxable salary defined in Kenya, and which components are included?

        In Kenya, taxable salary covers basic pay, allowances (unless exempt), overtime, bonuses, and benefits like housing or transport. Employer-provided perks (e.g., loans, gifts) may also be taxable. Deductions like NHIF, NSSF, or pension contributions reduce taxable income, which is taxed progressively up to 30%.

        What is included in the taxable salary calculation in Pakistan, and are there specific exemptions?

        In Pakistan, taxable salary includes basic pay, dearness allowance, and taxable allowances (e.g., housing, medical). Exemptions apply to certain allowances (like education or conveyance) and reliefs (e.g., ₹60,000 standard deduction). Tax is calculated on net income after deductions, with rates up to 25% for individuals.

        What’s the difference between taxable salary and wages, and how are they taxed?

        Taxable salary refers to the portion of earnings subject to income tax (e.g., basic pay + taxable allowances), while wages broadly include all compensation (salary, bonuses, overtime, tips). Not all wages are taxable—some may be exempt (e.g., gifts under ₹5,000 in India) or taxed separately (e.g., bonuses). Tax is applied to the taxable portion after deductions.

        How is taxable salary determined in the Philippines, and which benefits are tax-free?

        In the Philippines, taxable salary includes basic pay, 13th-month pay, cash gifts/gratuities, and taxable allowances (e.g., housing, transportation). Exemptions apply to certain benefits like de minimis fringe benefits (e.g., ₱500/month for meals) or SSS contributions. Tax is computed on gross income minus personal/exemption deductions (₱50,000 standard + dependents).

        What does "taxable salary" mean in the context of IRS Form P9 (Philippines), and how is it reported?

        On the Philippine BIR Form P9 (Annual Income Tax Return), "taxable salary" is the gross compensation (salary + taxable allowances) minus personal/exemption deductions (₱50,000 + ₱25,000 per dependent). It excludes tax-free benefits (e.g., SSS, Pag-IBIG, PhilHealth premiums paid by the employer). The net amount is taxed based on progressive rates (5%–35%).

        Leave a Comment

        Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Voltefac.