What Is The Currency Of Republic Of Ireland Explained
Table of Contents
- Currency Basics and Official Status of the Euro in the Republic of Ireland
- Legal Tender Status and Historical Adoption
- Issuance and Regulation by the European Central Bank and Central Bank of Ireland
- Design Features of Euro Banknotes and Coins: Cultural and Historical Elements
- Comparison Table: Euro Denominations, Dimensions, and Security Features
- The Economic Role and Usage of the Euro in the Republic of Ireland
- Functional Role in Daily Transactions and Trade
- Impact on Inflation, Purchasing Power, and Cross-Border Transactions
- Timeline of Key Economic Events Tied to the Euro’s Adoption
- Circulation Statistics and Regional Usage Patterns
- Historical Context and Transition of Ireland’s Currency
- Pre-Euro Currency: The Irish Punt and Its Evolution
- Transition Process: From Punt to Euro
- Political and Economic Debates Surrounding Euro Adoption
- Case Studies: Businesses and Individuals Affected by the Currency Switch
- Practical Considerations for Travelers and Residents Using the Euro in Ireland
- Essential Tips for Managing Euros in Ireland
- Step-by-Step Guide to Obtaining Euros in Ireland
- Cost of Living Comparison: Euros vs. USD/GBP
- Regions Where Euros Are Exclusively or Primarily Used
- Cultural and Symbolic Significance of the Euro in the Republic of Ireland
- Euro Design Elements Reflecting Irish Heritage
- Public Perception and Debates on National Identity
- Irish Slang, Humor, and Pop Culture References to Money
- Media and Pop Culture Depictions of the Euro and Financial Themes
- Technical and Legal Framework Governing the Euro in the Republic of Ireland
- Legal Framework and Anti-Counterfeiting Measures
- Collaboration Between the Central Bank of Ireland and the ECB
- Consumer Rights and Dispute Resolution for Euro Transactions
- FAQ
- What is the official currency of the Republic of Ireland?
- What is the unit of currency in the Republic of Ireland?
- What is the main unit of currency in the Republic of Ireland?
- What currency does the Republic of Ireland use?
- What currency does the Republic of Ireland use today?
- What was the Republic of Ireland’s official unit of currency in 2000?
The Republic of Ireland’s economic identity is deeply intertwined with the euro, a currency that transcends borders while reflecting its unique cultural heritage. As one of the earliest adopters of the single European currency in 2002, Ireland seamlessly transitioned from the Irish punt, embedding the euro into daily life—from bustling Dublin streets to remote Gaeltacht regions. Beyond its functional role as legal tender, the euro in Ireland carries symbolic weight, featuring indigenous designs like the harp on banknotes and Celtic motifs on coins, bridging national pride with European integration.
This exploration delves into the euro’s operational mechanics, from its issuance by the European Central Bank and Central Bank of Ireland to its practical impact on inflation, trade, and cross-border transactions, particularly in the post-Brexit era. Historical context reveals the political and economic debates surrounding its adoption, while cultural insights uncover how Irish humor, media, and public sentiment shape perceptions of the currency. For travelers, residents, and businesses alike, understanding the euro’s intricacies—whether navigating ATMs, deciphering security features, or appreciating its design—is essential to fully grasp its role in modern Ireland.
Currency Basics and Official Status of the Euro in the Republic of Ireland
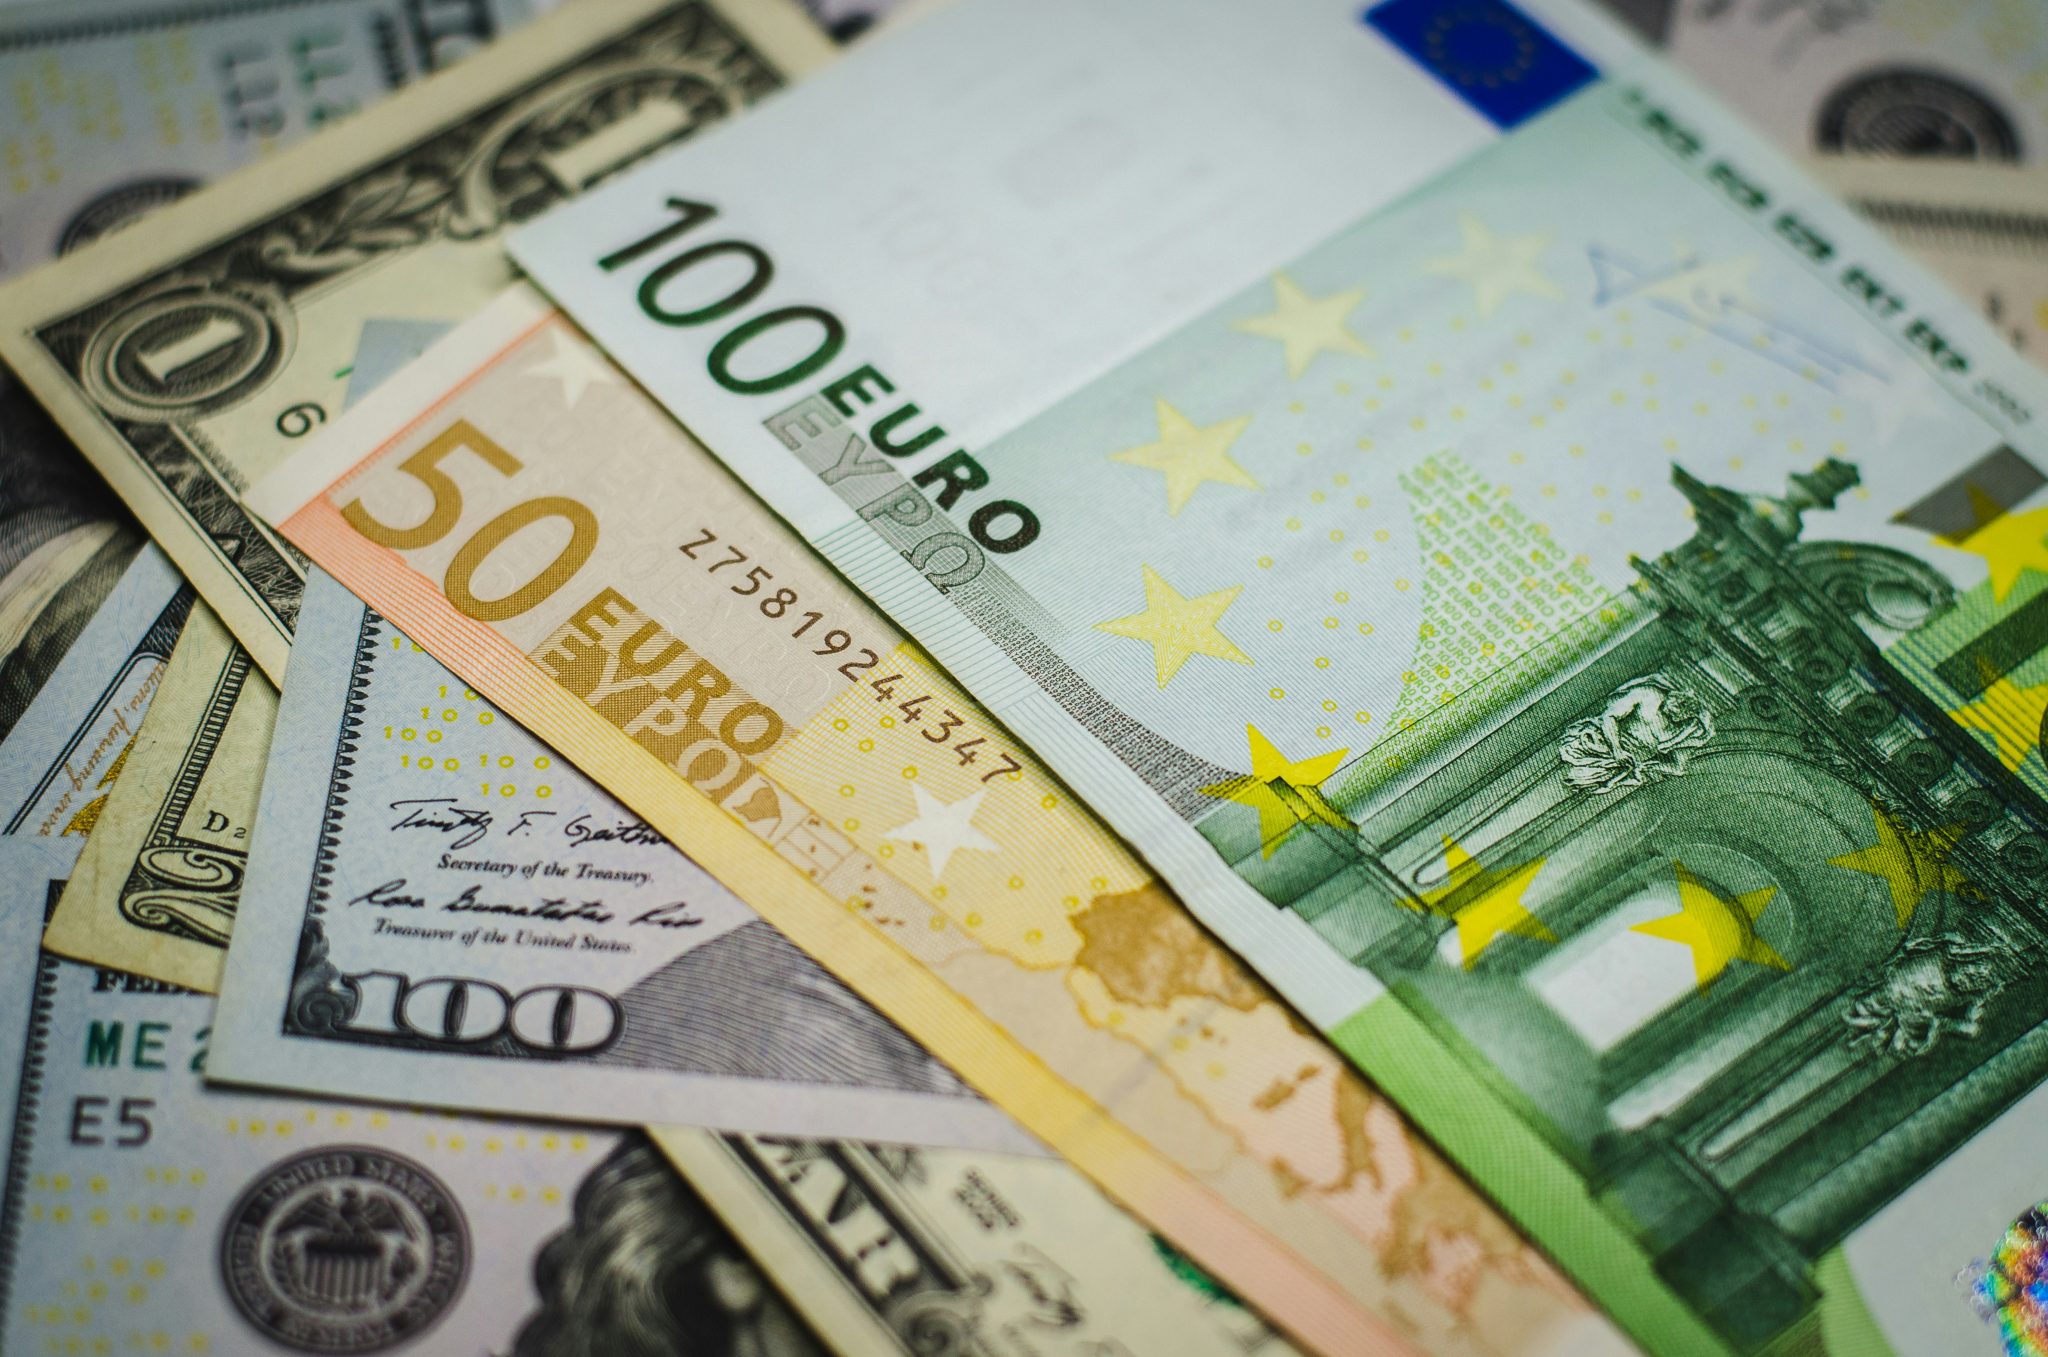
The Republic of Ireland adopted the euro (€) as its official currency on January 1, 1999, following its participation in the European Union’s (EU) Economic and Monetary Union (EMU). The euro replaced the Irish pound (IR£), which had been the legal tender since 1928, following Ireland’s independence from the United Kingdom. The transition to euro cash occurred on January 1, 2002, marking a significant economic and political integration with the broader European monetary system. The euro’s adoption in Ireland aligns with EU regulations, ensuring price stability, cross-border trade facilitation, and compliance with the Maastricht Treaty criteria.The euro is the sole legal tender in the Republic of Ireland, governed by the European Central Bank (ECB) and the Central Bank of Ireland (CBI). The ECB oversees monetary policy, currency issuance, and inflation control across the eurozone, while the CBI manages national implementation, including banknote distribution, counterfeit detection, and public information campaigns. Ireland’s adherence to the euro system reflects its commitment to fiscal discipline, as outlined in the Stability and Growth Pact, which limits national deficits and debt levels to maintain economic convergence within the EU.
Legal Tender Status and Historical Adoption
The Irish pound circulated for over seven decades before its phased replacement by the euro. The transition was structured in two phases:1. January 1, 1999: The euro was introduced as an electronic currency for financial transactions, while the Irish pound remained in physical circulation.
2. January 1, 2002: Euro banknotes and coins entered circulation, with the Irish pound officially withdrawn from use by February 9, 2002. Citizens retained the right to exchange Irish pound notes and coins at the CBI until February 2015, with a final deadline for coin exchange set at February 2018.
The euro’s adoption in Ireland was supported by public awareness campaigns, including the "Tell Them Euro" initiative, which educated businesses and consumers on the transition. The CBI played a pivotal role in ensuring smooth circulation, including the distribution of 1.2 billion euro coins and 13 million banknotes in the initial phase. The euro’s stability in Ireland is further reinforced by the Irish National Accounts, which report GDP and inflation in euros, aligning with EU statistical standards.
Issuance and Regulation by the European Central Bank and Central Bank of Ireland
The euro’s issuance in Ireland follows a decentralized yet harmonized system under the European System of Central Banks (ESCB). While the ECB designs and authorizes euro banknotes, national central banks (NCBs) like the CBI are responsible for their production, distribution, and withdrawal. The CBI operates as the sole distributor of euro banknotes in Ireland, managing a network of 1,800 ATMs and 2,500 bank branches to ensure availability. Euro coins, however, are minted by the National Bank of Belgium (for common designs) and distributed through commercial banks, which are obligated to stock them.The CBI enforces strict security protocols to combat counterfeiting, including:
The euro’s value is backed by the collective financial strength of the eurozone, with the ECB’s mandate to maintain price stability (defined as an inflation rate below 2%). Ireland’s participation in the Eurogroup and Eurosystem ensures its voice in monetary policy decisions, though national fiscal policies remain under domestic oversight.
Design Features of Euro Banknotes and Coins: Cultural and Historical Elements
Euro banknotes and coins feature pan-European designs with national variations in coinage. Ireland’s euro coins incorporate distinct motifs reflecting its heritage, wildlife, and technological achievements, while banknotes showcase EU cultural landmarks with no country-specific imagery.Euro Banknotes (Common Design for All Eurozone Countries)
Euro banknotes are designed to resist counterfeiting and symbolize European unity. Each denomination (€5 to €500) includes:
Euro Coins (Irish National Side Designs)
Ireland’s euro coins feature unique designs on their national side, approved by the CBI and the Government of Ireland. The motifs include:
The €1 and €2 coins also include 12-star EU emblems and the year of minting, ensuring compliance with eurozone standards.
Comparison Table: Euro Denominations, Dimensions, and Security Features
The following table summarizes the physical and security attributes of euro banknotes and coins, including their dimensions, colors, and anti-counterfeiting measures.| Denomination | Type | Dimensions (mm) | Color | Key Security Features | Material | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| €5 | Banknote | 120 × 62 | Grey |
|
Cotton-based paper | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| €10 | Banknote | 127 × 67 | Red |
|
Cotton-based paper | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| €20 | Banknote | 133 × 72 | Blue |
|
Cotton-based paper | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| €50 | Banknote | 140 × 77 | Orange |
|
Cotton-based paper | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| €100 | Banknote | 147 × 82The Economic Role and Usage of the Euro in the Republic of Ireland
The euro serves as the primary medium of exchange in the Republic of Ireland, embedding the country within the Eurozone’s economic framework. Its adoption has reshaped daily transactions, trade dynamics, and cross-border financial interactions, particularly in the context of post-Brexit economic adjustments. The euro’s integration into Ireland’s economy has influenced inflation trends, purchasing power, and the efficiency of cross-border transactions, while its physical circulation reflects regional usage patterns and economic behavior. The euro’s role extends beyond domestic transactions, acting as a stabilizer in trade with the United Kingdom and other Eurozone nations. Its acceptance in public services, private commerce, and financial institutions underscores its indispensable position in Ireland’s economic infrastructure. Below, the discussion explores the euro’s functional impact, its economic consequences, and key historical milestones tied to its adoption, alongside statistical insights into its circulation and usage trends. Functional Role in Daily Transactions and TradeThe euro is universally accepted in the Republic of Ireland for all transactions, including retail purchases, utilities, transportation, and public services. Cash transactions remain prevalent in sectors such as hospitality, agriculture, and small businesses, where digital payments are less common. According to the Central Bank of Ireland (2023), approximately 40% of all transactions in Ireland involve cash, with euro coins and banknotes circulating at a rate of €1.5 billion annually. The euro’s dual role as a legal tender and a global reserve currency ensures liquidity in both domestic and international trade, facilitating seamless cross-border commerce with the UK, the EU, and beyond.Trade with the UK, Ireland’s largest export market, has been significantly influenced by the euro’s adoption. Post-Brexit, the absence of a common currency has introduced complexities in pricing, invoicing, and currency conversion, particularly for SMEs. However, the euro’s stability and widespread acceptance mitigate risks associated with exchange rate volatility. For instance, Irish exporters to the Eurozone benefit from zero transaction costs when settling invoices in euros, reducing operational expenses. Conversely, trade with non-EU partners, such as the US or Switzerland, often requires currency conversion, adding a layer of financial overhead. Impact on Inflation, Purchasing Power, and Cross-Border TransactionsThe introduction of the euro has had a measurable effect on Ireland’s inflation rates, purchasing power, and economic resilience. Between 2002 and 2023, Ireland’s harmonized index of consumer prices (HICP) averaged 1.8% annually, slightly below the Eurozone average of 2.1%, reflecting the country’s relatively stable price environment. However, periods of economic stress—such as the 2008 financial crisis—exacerbated inflationary pressures, with HICP peaking at 4.6% in 2008 due to housing market collapse and fiscal austerity measures.The euro’s adoption has also influenced purchasing power, particularly in sectors sensitive to import costs. For example, energy prices, denominated in euros, have fluctuated in tandem with global commodity markets, impacting household budgets. The Central Statistics Office (CSO) reports that household energy expenditure in Ireland increased by 35% between 2019 and 2023, partly attributable to euro-denominated fuel and electricity costs. Meanwhile, the euro’s stability has strengthened Ireland’s export competitiveness, with agricultural and pharmaceutical sectors benefiting from predictable pricing in Eurozone markets. Cross-border transactions with the UK have been particularly affected by the euro’s role since Brexit. The Bank of England (2022) estimates that €120 billion in annual trade between Ireland and the UK involves euro payments, despite the UK’s exit from the Eurozone. Irish businesses often invoice in euros to simplify transactions, while UK importers bear currency conversion fees. This dynamic has led to a 15% increase in euro-denominated trade settlements since 2020, as companies seek to avoid sterling volatility. Timeline of Key Economic Events Tied to the Euro’s AdoptionThe euro’s integration into Ireland’s economy has been marked by pivotal events that shaped its economic trajectory. Below is a chronological overview of significant milestones:
Circulation Statistics and Regional Usage PatternsThe euro’s physical circulation in Ireland reflects economic behavior, with certain denominations and regions showing higher usage rates. The Central Bank of Ireland (2023) provides the following insights:
Historical Context and Transition of Ireland’s CurrencyThe Republic of Ireland’s monetary history reflects broader economic and political transformations, culminating in its adoption of the euro. Before the euro, the Irish punt (officially the Irish pound) served as the national currency for over 200 years, evolving through periods of stability, devaluation, and structural reforms. The transition to the euro in 2002 marked a pivotal shift, driven by economic integration, political alignment with the EU, and the need for monetary stability in an increasingly globalized economy. This section examines the pre-euro currency landscape, the phased adoption process, and the societal and economic impacts of the switch.Pre-Euro Currency: The Irish Punt and Its EvolutionThe Irish punt, introduced in 1928 following the establishment of the Irish Free State, replaced the British pound sterling as the official currency. Its value was initially pegged to sterling at a 1:1 ratio, but this arrangement proved unsustainable amid Ireland’s economic challenges. Over the decades, the punt underwent significant devaluations and reforms to align with Ireland’s economic realities:- 1931–1979: Economic Autonomy and Devaluations - 1979–1999: Joining the Exchange Rate Mechanism (ERM) and Stability The punt’s final years were characterized by preparations for the euro, including the issuance of euro-compatible banknotes and coins in 1999, though physical circulation began only in 2002. Transition Process: From Punt to EuroThe shift from the Irish punt to the euro was a meticulously planned, multi-phase process involving legal, financial, and public engagement strategies. Ireland’s adoption followed the euro’s launch in 1999, with full circulation commencing on 1 January 2002. The transition spanned three critical phases:- Phase 1: Legal and Financial Preparation (1999–2001) - Phase 2: Public Awareness Campaigns - Phase 3: Full Circulation and Sunset of the Punt (2002) The transition was notably smooth, with minimal disruption attributed to Ireland’s strong banking infrastructure and proactive public messaging. Political and Economic Debates Surrounding Euro AdoptionThe decision to adopt the euro in Ireland was contentious, with proponents and opponents presenting compelling arguments during the 2001 referendum. The vote passed with 63% in favor, but debates centered on sovereignty, economic flexibility, and long-term stability."The euro is not just a currency; it is a symbol of Ireland’s place in Europe. Adopting it will strengthen our economy, reduce transaction costs, and ensure our competitiveness in a single market."Key arguments from both sides included: - Pro-Euro (Economic and Political Integration) - Anti-Euro (Sovereignty and Economic Risks) The referendum’s outcome reflected Ireland’s economic confidence in the late 1990s, fueled by the "Celtic Tiger" boom. However, the 2008 financial crisis later exposed vulnerabilities in Ireland’s eurozone membership, particularly regarding bailout conditions and austerity measures. Case Studies: Businesses and Individuals Affected by the Currency SwitchThe transition to the euro had varied impacts across sectors, with some entities facing operational challenges while others benefited from streamlined transactions. Notable examples include:- Small and Medium Enterprises (SMEs) - Tourism and Hospitality - Financial Services Practical Considerations for Travelers and Residents Using the Euro in IrelandThe euro (€) serves as the primary currency in the Republic of Ireland, facilitating seamless transactions for both residents and visitors. Understanding practical aspects—such as exchange methods, fee structures, and regional payment norms—ensures cost efficiency and avoids financial pitfalls. This section provides actionable guidance on accessing euros, optimizing payment methods, and navigating Ireland’s economic landscape, including comparisons with other major currencies.Essential Tips for Managing Euros in IrelandTravelers and residents should prioritize minimizing transaction costs and leveraging widely accepted payment methods. Ireland’s economy relies heavily on card payments, particularly in urban centers, though cash remains useful in rural areas and tourist-dependent regions. Key considerations include:- Exchange Rates and Fees: Dynamic exchange rates apply when converting foreign currencies to euros, particularly at airports or exchange bureaus. Institutions like Revolut, Wise (formerly TransferWise), or local banks typically offer competitive rates with lower hidden fees compared to high-street exchange offices. For optimal exchange rates, pre-load euros onto a multi-currency debit/credit card (e.g., Wise or Revolut) or withdraw from ATMs affiliated with Euronet or Travelex in cities, which often provide better rates than airport counters. Step-by-Step Guide to Obtaining Euros in IrelandAccessing euros efficiently requires selecting the right method based on location, urgency, and cost. Below is a structured approach to acquiring euros with minimal fees:1. ATM Withdrawals 2. Bank Branches and Currency Exchange Bureaus 3. Online and Mobile Banking 4. Currency Exchange Scams to Avoid Cost of Living Comparison: Euros vs. USD/GBPIreland’s cost of living varies significantly depending on location, with Dublin being 20–30% more expensive than regional cities like Cork or Galway. Below is a comparative breakdown of common expenses in euros, USD, and GBP (as of 2024 estimates, using 1 EUR ≈ 1.10 USD ≈ 0.85 GBP):
Dublin’s cost of living rivals London or New York, with housing being the most significant expense. Regional cities offer 20–40% savings on rent and groceries, making them preferable for long-term residents. Regions Where Euros Are Exclusively or Primarily UsedWhile Northern Ireland uses the British pound (GBP), the Republic of Ireland’s euro dominance extends to specific zones where sterling is either unaccepted or impractical. Key areas include:1. Republic of Ireland (Entire Country) 2. Border Regions Near Northern Ireland
Cultural and Symbolic Significance of the Euro in the Republic of IrelandThe euro’s adoption in the Republic of Ireland reflects both its economic integration within Europe and its deeper cultural resonance. While the euro is a pan-European currency, its circulation in Ireland has sparked discussions on national identity, artistic representation, and public sentiment. The currency’s design incorporates elements of Irish heritage, though these are often subtle compared to more overt national symbols. Public perception varies widely, with debates centering on sovereignty, economic pragmatism, and the symbolic weight of a shared currency. Irish humor and media frequently reference financial themes, offering a glimpse into societal attitudes toward money, spending, and economic realities.The euro’s banknotes and coins feature motifs that subtly acknowledge Ireland’s cultural contributions, blending European unity with national pride. Public reactions to the euro range from pragmatic acceptance to critiques of lost national identity, while Irish slang and pop culture reflect a lived experience of managing finances in a globalized economy. Euro Design Elements Reflecting Irish HeritageThe euro’s banknotes and coins incorporate artistic and historical references that indirectly honor Ireland’s cultural legacy. While the euro lacks overtly nationalistic designs—unlike currencies such as the pound sterling or the Swiss franc—its European-wide aesthetic includes motifs that resonate with Irish art and history.Banknotes: Coins: Public Perception and Debates on National IdentityThe euro’s introduction in Ireland (2002) coincided with ongoing debates about sovereignty, economic policy, and cultural distinctiveness. While the currency facilitated trade and travel within Europe, its adoption was not universally celebrated, particularly among those who viewed it as a symbol of economic subordination to Brussels.Key Debates: Public Sentiment Over Time: Irish Slang, Humor, and Pop Culture References to MoneyIrish culture has a long tradition of wit and satire regarding money, often reflecting economic realities with humor. The euro’s arrival introduced new phrases and jokes, blending traditional Irish financial idioms with modern European experiences.Common Irish Slang and Idioms: Humor and Satire: Media and Pop Culture Depictions of the Euro and Financial ThemesIrish media and entertainment often explore financial themes, from economic crises to everyday struggles with money. The euro’s role in these narratives reflects broader societal attitudes toward globalization, austerity, and national resilience.Television: Music: > But we’re still the same old Irish mob, > Whether it’s pounds or euros, > We’ll spend it all on booze and trouble!"* Technical and Legal Framework Governing the Euro in the Republic of IrelandThe Republic of Ireland’s adoption of the euro is underpinned by a robust legal and technical framework that ensures currency integrity, fraud prevention, and seamless cross-border transactions. Ireland, as a Eurozone member, adheres to European Union (EU) directives and regulations enforced by the European Central Bank (ECB) and the Central Bank of Ireland (CBI), while also implementing national measures to combat counterfeiting and financial crime. This framework integrates anti-counterfeiting protocols, legal recourse for consumers, and technological advancements to modernize euro usage in line with global financial standards.The legal and technical ecosystem governing the euro in Ireland operates through a multi-layered system, combining EU-wide policies with national enforcement mechanisms. The Legal Tender and Currency Act 2017 and Central Bank Acts establish the euro as Ireland’s sole legal tender, while the Criminal Justice (Money Laundering and Terrorist Financing) Act 2010 and EU Counterfeiting Directive (2019/713) mandate strict penalties for counterfeit currency circulation. Collaboration between the CBI and ECB ensures compliance with Eurozone security features, including holograms, microtext, and color-shifting ink, while digital tools enhance traceability and fraud detection. Legal Framework and Anti-Counterfeiting MeasuresThe Republic of Ireland enforces anti-counterfeiting laws through EU Regulation (EC) No 1338/2001 and National Legislation, which criminalize the production, distribution, or possession of counterfeit euro banknotes and coins. Under Irish law, Section 15 of the Criminal Justice Act 1994 and Section 3 of the Central Bank Acts classify counterfeiting as an offense punishable by:The Central Bank of Ireland (CBI) works with An Garda Síochána (Irish Police) to investigate counterfeit cases, while the ECB’s Euro Counterfeit Intelligence Centre (ECIC) provides forensic analysis and intelligence sharing. Banknote authenticity tests, such as the "tilt test" (observing color shifts) and "touch test" (feeling raised printing), are promoted through public awareness campaigns to deter counterfeit use. Key Legal Provisions for Counterfeit Euro Handling in Ireland: Collaboration Between the Central Bank of Ireland and the ECBThe Central Bank of Ireland (CBI) serves as the national competent authority (NCA) for euro implementation, coordinating with the ECB to maintain currency authenticity and supply chain integrity. Key collaborative mechanisms include:- Currency Supply and Distribution - Fraud Detection and Intelligence Sharing - Regulatory Compliance and Audits ECB-CBI Collaboration Framework: Consumer Rights and Dispute Resolution for Euro TransactionsIrish consumers are protected under EU and national laws governing euro transactions, including payment errors, card fraud, and counterfeit refusals. The following table outlines key rights and recourse mechanisms:
|


Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Voltefac.